|
Is Vanguard FDIC and SIPC Insured in 2026?
|
Is Vanguard FDIC Insured?
Vanguard provides both SIPC protection and FDIC-insured options for holding cash. Here is how these protections work:
Vanguard itself is not a bank and does not provide conventional bank checking or savings accounts. Instead, it offers bank sweep programs that move eligible cash to participating banks.
FDIC insurance applies to qualifying deposits maintained at participating banks. Through Vanguard, the Vanguard Cash Deposit settlement option and the Vanguard Cash Plus Account bank sweep provide FDIC insurance through program banks.
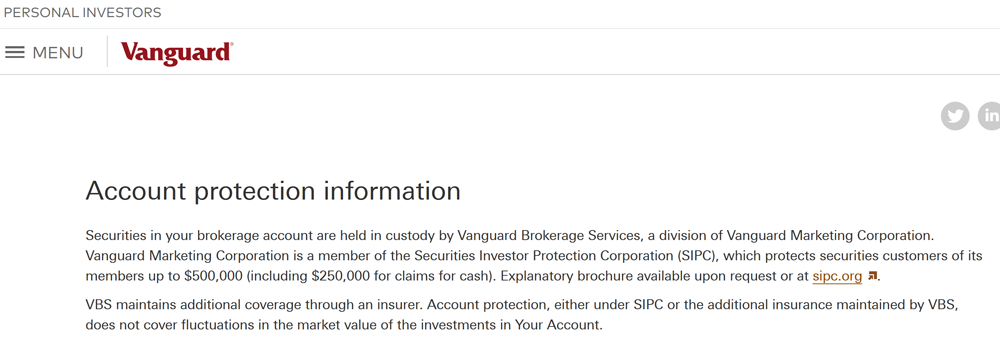
Eligible cash and securities maintained through Vanguard Brokerage Services qualify for SIPC protection. Coverage is limited to $500,000 for each separate capacity. No more than $250,000 of that amount can cover claims for cash.
Calculating SIPC Coverage at Vanguard
SIPC coverage is generally determined per customer and per separate capacity at each brokerage firm. As a result, accounts at different brokerage firms can have separate protection, while accounts maintained in the same capacity at one firm are usually combined when calculating coverage. There are some exceptions and additional rules, however.
For instance, SIPC rules provide Traditional IRAs with protection separate from taxable individual accounts, while Roth IRAs are also separate from Traditional IRAs.
Suppose you hold 2 IRAs at Vanguard (one Roth and one Traditional) along with 2 taxable individual accounts. You would have a total of $1.5 million in SIPC protection. The two retirement accounts would receive a combined $1 million of coverage ($500,000 for the Roth and $500,000 for the Traditional), while the two individual taxable accounts would share another $500,000 of protection.
If one of those taxable accounts is instead a qualifying joint account, it would receive its own $500,000 coverage limit, bringing the total SIPC protection for the taxable accounts to $1 million.
Vanguard And Top Competitors
Money Market Settlement Fund
Each Vanguard brokerage account includes a settlement fund. Vanguard Federal Money Market Fund (VMFXX) is Vanguard’s default settlement fund, while Vanguard Cash Deposit is the other settlement option. Uninvested funds are automatically swept into the settlement option you select.
Since VMFXX is a security, it qualifies for the securities portion of SIPC coverage instead of being subject to the $250,000 limit for cash claims. The fund is a money market mutual fund that aims to maintain a $1.00 share price, although maintaining that value is not guaranteed.
There are two Vanguard settlement fund options: Vanguard Federal Money Market Fund (VMFXX) and Vanguard Cash Deposit. Vanguard Cash Deposit operates as a bank sweep, with eligible balances receiving FDIC insurance through participating program banks.
Account Example
As an example of Vanguard’s SIPC protection, assume you have a taxable brokerage account containing $600,000 in assets. The account consists of the following:
$230,000 in Tesla stock
$70,000 in GLD, the gold ETF
$300,000 in VMFXX, the settlement fund
If Vanguard were to fail and all $600,000 of these securities were missing, standard SIPC protection for this individual account would be capped at $500,000. Since VMFXX is classified as a security rather than cash, it would not be subject to SIPC’s $250,000 cash-claim limit. The other $100,000 would exceed the standard SIPC coverage maximum.
It is also important to remember that customer securities held in custody are not corporate assets belonging to Vanguard and ordinarily remain customer property if a brokerage firm fails. SIPC is intended to restore eligible securities and cash that are missing from customer accounts when a SIPC-member brokerage firm enters liquidation.
Supplemental Insurance at Vanguard
Vanguard does have an auxiliary insurance policy through Lloyd’s of London and London Company Insurers. It adds a second layer of protection to a brokerage account if, and only if, SIPC protection is exhausted.
The secondary insurance policy is good for up to $49.5 million per account. There is an aggregate maximum of $250 million. That means the insurance policy will shell out a quarter of a billion dollars at most across all accounts that have maxed out SIPC coverage.
Going back to our example, the $100,000 of account value that is unprotected now should be protected by the supplemental insurance policy, assuming the aggregate limit is not exhausted. After that point, there are no guarantees.
Written by Alex Bost
Updated on 8/31/2026.
|